In This Article
A rear-end collision, an emergency room visit, or a burst pipe can turn an ordinary Tuesday into a bill that costs thousands. Insurance helps households share the financial risk of those costly events instead of carrying it alone.
An insurance policy is a contract. You pay premiums, and the insurer agrees to pay for certain covered losses under stated terms. The details matter, including deductibles, limits, exclusions, and deadlines.
What Is Insurance, and How Does It Work?
Insurance has two sides. The insurer is the company that takes on defined risks. The policyholder is the person or business buying protection. Their policy explains what the contract covers, what it excludes, and how much it may pay.
First, you choose coverage and pay a premium, usually monthly, semiannually, or annually. If a covered event happens, you file a claim, which asks the insurer to review the loss and pay under the policy.
Risk pooling makes the model work. Many customers pay premiums into the same pool. The insurer uses that money to pay claims for the smaller number of people who suffer covered losses.
For example, a covered repair may cost $6,000. With a $1,000 deductible, you would generally pay the first $1,000. The policy could pay the remaining $5,000, subject to its limits and terms.
Insurance doesn’t pay for every problem. Intentional damage, excluded events, missed payments, and losses above a coverage limit can change or eliminate payment. It fits best within a beginner’s guide to personal finance, alongside savings, debt management, and a spending plan.
How Premiums, Deductibles, and Coverage Limits Shape Costs
A premium is the price of coverage. Insurers set it using details tied to the policy, such as your location, driving history, age, health, property value, prior claims, and selected protection.
A lower premium often comes with a higher deductible. That choice can reduce monthly costs, but it may sting when you need to file a claim. Pick a deductible you could pay without draining your checking account.
The most an insurer will pay for a covered loss is the coverage limit. Health plans may also use copayments and coinsurance, which split some costs between you and the plan. The ACA Marketplace coverage guide explains how deductibles, copayments, and coinsurance affect health plan costs.
What Happens When You File an Insurance Claim
Protect people first, then prevent added damage when it is safe to do so. Photograph the scene, save receipts, and promptly contact the insurer. Most policies set deadlines for reporting a loss.
An adjuster may inspect damage, review records, and estimate the covered amount. Read the settlement carefully. If the insurer denies or reduces a claim, ask which policy language led to that decision.
Do not admit fault or throw away damaged property before getting guidance from the insurer, unless safety requires immediate action.
The Main Types of Insurance and the Risks They Help Cover
Different policies protect against various financial shocks. The right mix depends on your household, assets, health, income, and legal obligations.
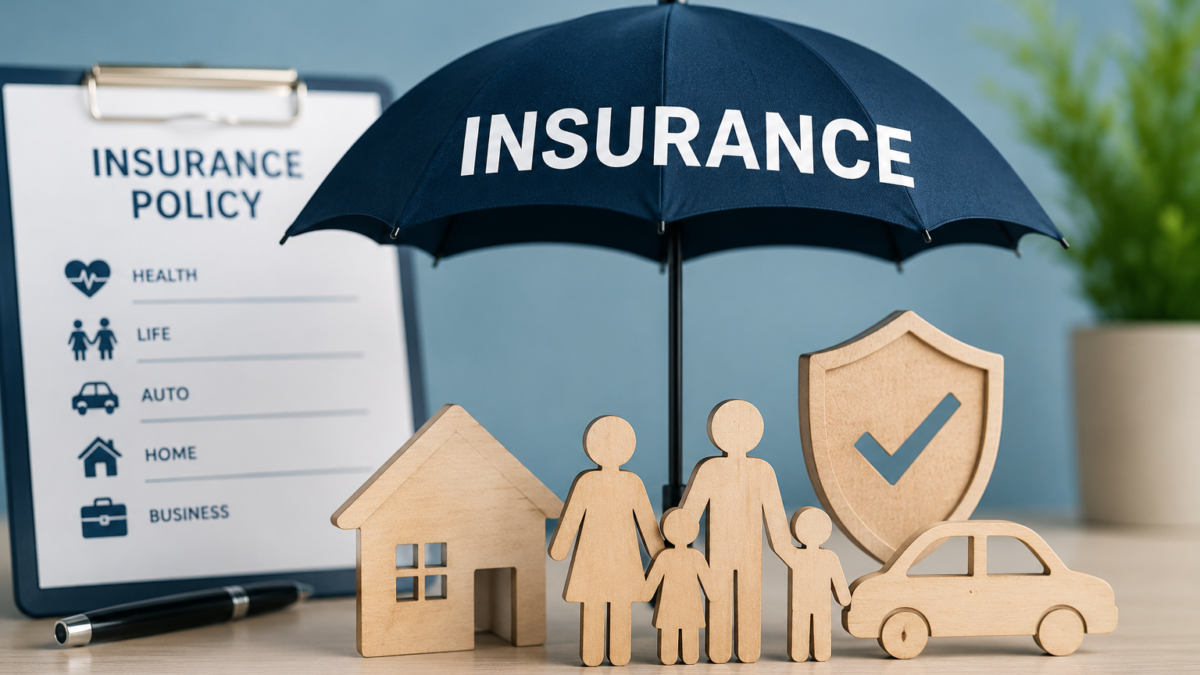
Auto insurance can pay for vehicle damage, injuries, and liability if you harm someone else or their property. States set their own minimum requirements, but minimum liability limits may not cover a serious crash.
Homeowners and renters insurance can protect belongings and personal liability. Homeowners coverage may also help repair the structure, while renters coverage does not insure the building itself.
Health insurance helps with medical costs. Life insurance can replace income or support dependents after a death. Disability insurance replaces part of your income after a qualifying illness or injury. Long-term care insurance may help pay for extended assistance that health insurance often does not cover.
Liability protection covers harm you cause to others. Coverage for your car, home, medical care, or income addresses your household’s direct expenses. Lenders, employers, and state laws may require certain policies, but no single policy suits every person.
Which Insurance Risks Deserve Priority?
Start with losses that could overwhelm your finances: major medical bills, a liability lawsuit, a destroyed home, or months without income. Then consider dependents, debts, current savings, employer benefits, and property you own.
Savings and insurance have separate jobs. An emergency fund handles smaller costs and immediate bills. Insurance addresses large covered losses that would be difficult to absorb alone. Use guidelines for emergency fund savings to build the cash cushion that supports your coverage.
How to Choose Insurance Without Paying for the Wrong Coverage
Estimate what your household could not comfortably pay out of pocket. Next, review policies you already have, including benefits through work. Duplicate coverage can waste money, while gaps can leave you exposed.
Compare quotes from several reputable insurers, but don’t stop at the premium. Check deductibles, coverage limits, exclusions, renewal terms, and cancellation rules. Ask direct questions about what would happen in a common loss.
The cheapest policy may carry a deductible or limit that makes it weak protection. Check your state’s insurance department for licensing, complaint information, and company details. Discounts matter only after the coverage itself makes sense.
Review policies after marriage, a new child, a home purchase, a job change, or a major shift in income. Losing job-based health coverage can also create a decision point, and COBRA coverage rules outline one possible continuation option.
Insurance Mistakes That Can Leave You Exposed
Common errors often appear in small print or old paperwork:
- Choosing liability or property limits that are too low for your assets and risks.
- Focusing on the premium while ignoring exclusions and the deductible.
- Letting a policy lapse or withholding important facts on an application.
- Forgetting to update beneficiaries, home values, or a list of valuable belongings.
Keep policy documents, purchase receipts, photos, and claim records in a secure digital folder. Once a year, compare your limits with your current life, property, and savings.
Final Thoughts
Insurance transfers selected financial risks to an insurer in exchange for premiums. Yet the policy’s limits, exclusions, and deductible decide what protection you truly have.
Please list the losses your household could not comfortably pay for, and then compare that list with your current coverage. Clear policy details matter more than a low price alone.