In This Article
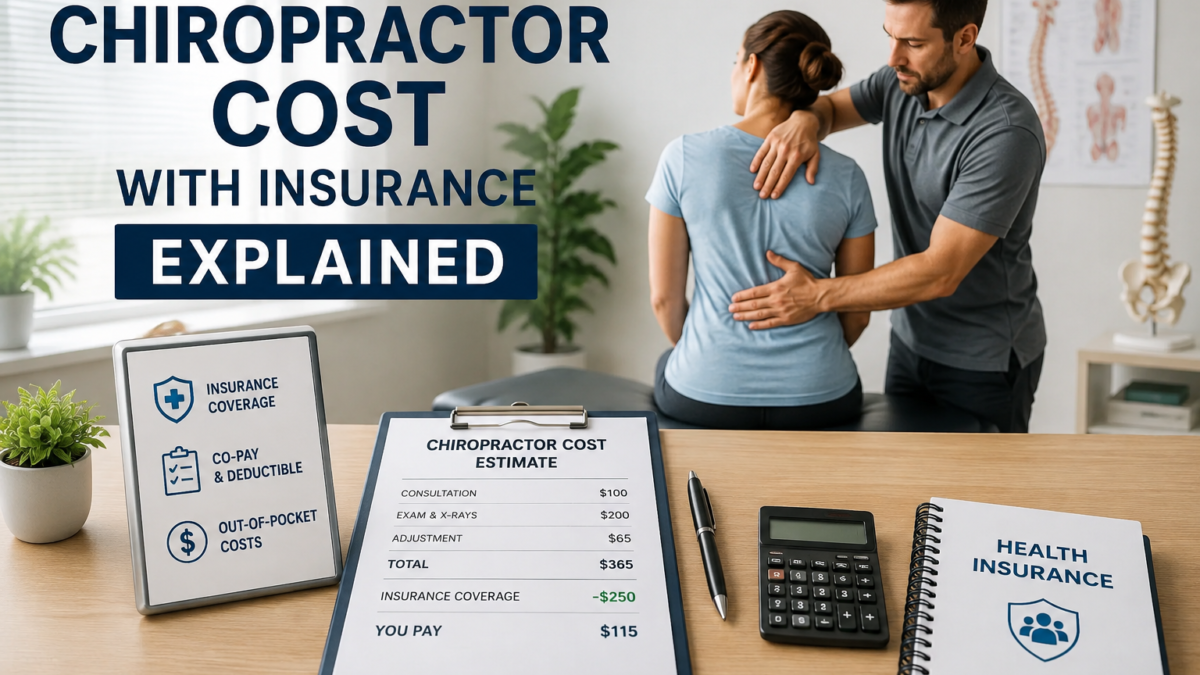
A chiropractic appointment may require a simple copayment or result in a larger bill. Your chiropractor cost depends on your plan, network status, deductible, copayments, coinsurance, and covered services.
Insurance terms can feel like a locked drawer of paperwork. A quick review of how health insurance works can help you estimate what you may owe before treatment begins.
Asking a few questions before booking can help prevent a surprise charge later.
Key Takeaways
- Your cost may be a fixed copay, coinsurance, or the full negotiated rate before you meet your deductible.
- In-network chiropractors usually cost less because they accept your insurer’s negotiated payment rate.
- Cash visits often run about $60 to $200, but prices vary by city, treatment, and clinic.
- Original Medicare covers limited spinal manipulation, not every service offered in a chiropractic office.
- Confirm coverage, visit limits, referral rules, and the office’s estimate before your appointment.
How Insurance Changes the Price of a Chiropractic Visit
The price printed on a chiropractor’s bill rarely tells the full story. The office may charge one amount, while your insurer recognizes a lower allowed amount under its contract. Your final responsibility depends on your deductible, copay, coinsurance, and network status.
The average cost of a chiropractic session is often about $60 to $200 before add-ons. An initial consultation, initial exam, imaging, or more involved treatment plan can raise the bill. A clinic in a major metro area may price an evaluation differently than a small office in a rural town.
Insurance can reduce the price of chiropractic care, but it doesn’t automatically make every visit inexpensive. A high-deductible plan may require you to pay the insurer’s negotiated rate until you reach the deductible.
How deductibles, copays, and coinsurance change the final bill
A deductible is the amount you pay for covered care before your plan begins sharing more of the cost. If an in-network chiropractic adjustment has an allowed amount of $90 and you haven’t met your deductible, you may owe the full $90, even when seeking pain relief or discussing spinal alignment.
A copay is a fixed amount. For example, your plan might charge $30 for each covered chiropractic visit, even when the allowed amount is higher.
Coinsurance is a percentage. If your plan pays 80% after the deductible and the allowed amount is $100, you would usually owe $20.
Before the deductible, compare the office’s cash rate with the allowed amount for a follow-up visit. A cash visit priced at $80 may cost less than an insurance claim priced at $120. Still, paying through insurance can help satisfy your deductible, so weigh the immediate bill against future deductible spending.
Why an in-network chiropractor usually costs less
In-network providers agree to a contracted payment rate with your insurer. They generally can’t bill you above that allowed amount for covered services, apart from your required cost share.
Out-of-network care works differently. Some plans pay a smaller share, apply a separate deductible, or provide no out-of-network benefit at all. The chiropractor may also bill you for the difference between the charge and your plan’s payment. That practice is called balance billing.
Call your insurer rather than relying only on a clinic website. Confirm the individual chiropractor, the exact office location, and the billing provider are all in network for your particular plan.
What Insurance Plans Usually Cover at a Chiropractic Visit
Many health plans cover chiropractic care when it meets the plan’s medical-necessity rules. However, a chiropractic appointment can include far more than an adjustment.
The initial exam, X-rays, massage therapy, acupuncture, electrical stimulation, physical therapy, spinal decompression, supplies, and follow-up visit may have different coverage rules. Some services may be excluded, while others require prior authorization. A plan may cover manipulation but not a broader spinal alignment service beyond that covered care.
Plans also may limit the number of covered visits each year. They can require a referral from your primary care clinician or documentation for a diagnosis such as acute low back pain or chronic pain. Coverage depends on the specific plan and medical records. Ask for an estimate before adding services beyond the adjustment.
A covered adjustment does not mean every item on the same visit is covered. Review each service before treatment begins.
Medicare chiropractic coverage and the 2026 cost
Original Medicare Part B has a narrow chiropractic benefit. It covers manual manipulation of the spine by a chiropractor to correct a vertebral subluxation, a condition where spinal joints do not move properly while joint contact remains intact. This benefit covers a chiropractic adjustment, not a general spinal alignment program.
For 2026, the Part B deductible is $283. After you meet it, you generally pay 20% of the Medicare-approved amount for covered manipulation. If Medicare approves $60 for a covered adjustment after the deductible, your share is $12 and Medicare pays $48. Verify current figures and benefits, since Medicare rules can change.
Medicare does not broadly cover chiropractic appointments. Chiropractor-ordered X-rays, massage therapy, acupuncture, extraspinal manipulation, and maintenance care usually fall outside this benefit. A 2026 Medicare chiropractic cost overview can help clarify the distinction between covered manipulation and other office services.
Medicaid, employer plans, and marketplace policies
Medicaid benefits for chiropractic care vary by state. One state may cover treatment for adults with strict visit limits, while another may restrict benefits or cover children under different rules. Referrals and prior authorization can also apply.
Employer plans and Marketplace policies set their own coverage terms. The Summary of Benefits and Coverage and full plan documents provide the clearest answer. If the wording feels unclear, call the member-services number on your insurance card and ask about the service before scheduling.
How to Find Out Your Exact Chiropractic Visit Cost
A short phone call can turn a vague estimate into a useful number. Before scheduling an initial consultation, call your health insurance plan, then ask the office how it will submit the claim.
Questions to ask the insurer and chiropractor
Use these questions when you call:
- Is this chiropractor in network for my exact plan and office location?
- Does chiropractic care apply to my deductible, and how much remains?
- Will I owe a copay or coinsurance for each covered visit?
- How many visits does my plan cover this year?
- Do I need a referral or prior authorization?
- Are the exam, X-rays, therapies, and maintenance visits covered?
- What billing codes will the office use, and what is the expected allowed amount?
Ask the clinic whether it can run a pre-visit benefit check under the correct National Provider Identifier. Request a written estimate when possible, including how the exam, adjustment, and add-on services affect your total cost of care. Save the estimate, receipt, explanation of benefits, and payment record in one folder.
An estimate isn’t a guarantee of payment. The insurer makes the final decision after receiving the claim, but an estimate still gives you a clear starting point for comparing choices.
Can you use HSA or FSA money for chiropractic care?
Treatment used to diagnose or treat a medical condition, such as documented back pain, may generally qualify as an eligible HSA or standard FSA expense. Adjustments and related treatment visits often qualify when they are medically necessary.
General wellness or maintenance services may not qualify under every account administrator’s rules. A limited-purpose FSA is usually reserved for dental and vision expenses, so it may not cover these bills.
Check your account administrator’s rules, and keep itemized receipts and any medical documentation it requests. It also helps to review how much to keep in an emergency fund before an unexpected medical need forces you to use a credit card.
Ways to Lower Your Out-of-Pocket Chiropractic Cost
Start by comparing chiropractic care coverage options and choosing in-network care when available. The contracted rate usually offers the most predictable price, but it isn’t always your final out-of-pocket cost, especially before meeting your deductible.
Next, ask the office for its self-pay rate and compare it with your insurance estimate. If the clinic is a cash-based practice, compare its posted rate with the insurer’s allowed amount and your deductible obligations. Review the cancellation and refund policy before prepaying, even if the clinic offers prompt-pay discounts or smaller visit packages.
Review every explanation of benefits after the claim processes. Check the provider name, service date, billing codes, allowed amount, insurer payment, and patient balance. These details should match the services you received. Call the insurer or billing office if a charge differs from the estimate or includes a service you didn’t receive.
Be careful with large treatment packages, and understand the clinical rationale and likely duration of your treatment plan before prepaying. An average cost per visit can mislead if you can’t use every session. Compare the total cost of care, including fees, unused visits, supplies, and possible noncovered services. Don’t purchase a package solely because it promises spinal alignment. Also evaluate a monthly membership for visit limits, automatic renewal, cancellation terms, and whether it includes only adjustments or additional services.
Handle Billing Problems Before They Grow
A denied claim for chiropractic care doesn’t always mean you must accept the first bill. Start by reading the explanation of benefits, which explains whether the insurer denied the service because of network status, authorization, coding, or coverage.
If the clinic made a billing error, ask it to correct and resubmit the claim. If the insurer denied a service despite prior confirmation, request the plan’s appeal instructions. An estimate or prior confirmation can support your case, but it isn’t always a guarantee of payment.
Gather the estimate, referral, authorization number, clinical notes, EOB, and billing correspondence. Keep calls organized with the date, representative’s name, and reference number.
Medical bills can pile up quickly, so clear records make it easier to challenge a mistake before it turns into a collection issue.
For Medicare beneficiaries, a detailed 2026 coverage explanation also shows why covered spinal manipulation and noncovered extras should be separated on the bill.
Frequently Asked Questions
How much does a chiropractor cost without insurance?
A chiropractic visit without insurance often costs about $60 to $200, depending on the clinic, location, treatment, and whether the visit includes an exam or imaging. Ask about the self-pay rate and any additional fees before treatment begins.
Does insurance cover chiropractic care?
Many health plans cover chiropractic adjustments when they meet the plan’s medical-necessity rules. Coverage may exclude exams, X-rays, massage, acupuncture, maintenance care, or other services, so confirm each service with your insurer.
Is an in-network chiropractor less expensive?
Usually, an in-network chiropractor costs less because the provider accepts the insurer’s negotiated allowed amount. You may still owe the full allowed amount before meeting your deductible, or a copay or coinsurance after the deductible.
Does Medicare pay for chiropractic visits?
Original Medicare Part B covers manual spinal manipulation to correct a vertebral subluxation, subject to the Part B deductible and 20% coinsurance after the deductible. It generally does not cover routine adjustments, massage therapy, X-rays, acupuncture, or other extras.
Can I use HSA or FSA funds to pay for chiropractic care?
Chiropractic treatment used to diagnose or treat a medical condition, such as documented back pain, may generally qualify for HSA or standard FSA funds. Wellness or maintenance visits may not qualify, so check your account administrator’s rules and keep itemized receipts.
A Clearer Way to Budget for Chiropractic Care
Your chiropractor cost with insurance comes down to the deductible, copay or coinsurance, provider network, covered services, and visit limits. Medicare covers a narrow form of spinal manipulation, while Medicaid rules differ by state, and HSA or FSA eligibility depends on medical care rules.
Before treatment begins, verify covered services for chiropractic care, then compare your deductible, network status, visit limits, and cash alternative. This comparison clarifies your total cost of care and expected out-of-pocket cost. A five-minute benefits check and office estimate can prevent a painful billing surprise.