In This Article
When you compare health insurance plans, a low monthly premium can look like the best deal until a doctor visit, prescription, or hospital stay raises your costs. A plan with a higher premium may cost less overall after deductibles, copays, coinsurance, and the out-of-pocket limit.
Comparing coverage means considering your providers, facilities, prescriptions, and medical needs. For individual and family plans, the health insurance marketplace offers qualified health plans under the Affordable Care Act. Medicare Advantage plans are separate coverage and aren’t evaluated through Marketplace comparisons.
Health insurance choices should support your budget and access to medical care. Compare each provider network and ensure you can find a doctor before focusing solely on premiums.
Key Takeaways
- Compare each plan’s annual premium, deductible, copays, coinsurance, and out-of-pocket maximum instead of focusing only on the monthly premium.
- Estimate total yearly costs under low-use, regular-care, and major-care scenarios, then consider whether you could afford the plan’s worst-case in-network expenses.
- Check that the specific plan and network you are considering cover your doctors, hospitals, specialists, labs, pharmacies, and prescriptions.
- Understand how HMO, PPO, EPO, and POS rules affect referrals, out-of-network care, travel, and access to providers.
- Check for premium tax credits and cost-sharing reductions from the Marketplace, and use official Marketplace information before enrolling.
How to Compare Health Insurance Plans Without Overpaying
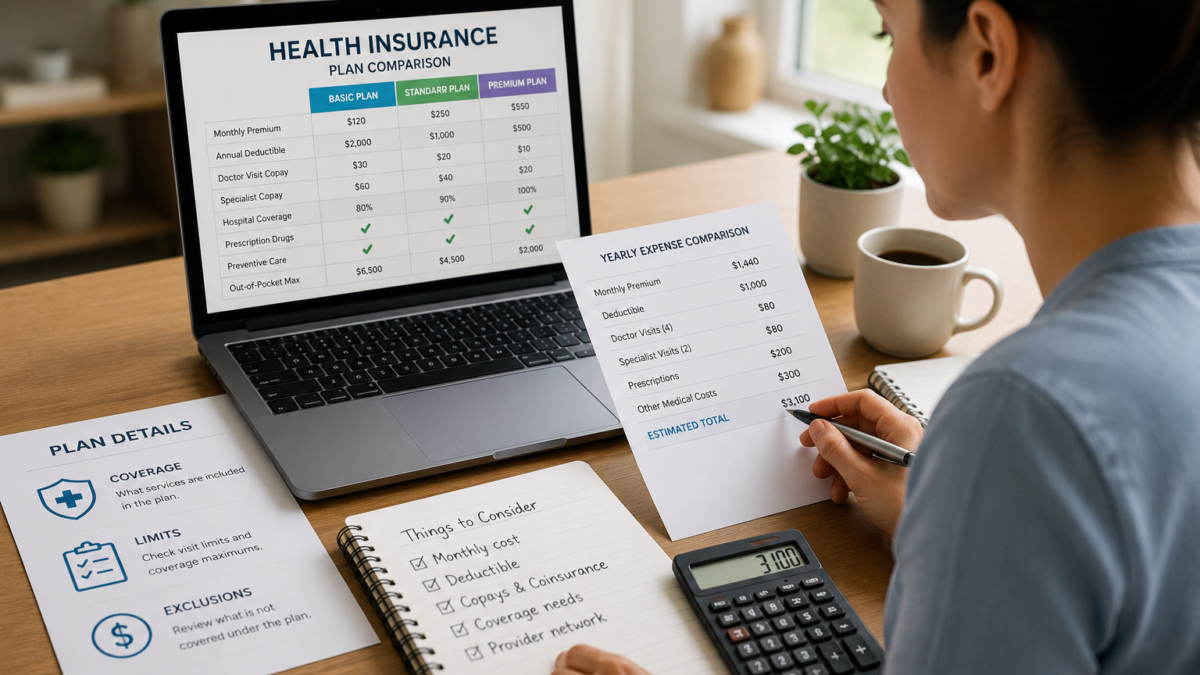
The lowest premium isn’t always the lowest-cost choice in health insurance. Total medical costs and medical care spending can matter more than the monthly payment alone. A plan with cheaper monthly payments may charge more when you need appointments, prescriptions, tests, or hospital care. Compare the same cost details for every option, then estimate what each plan could cost across a full year.
Compare premiums, deductibles, copays, and coinsurance.
Your premium is the amount you pay each month to keep coverage active, whether or not you use medical care. Multiply it by 12 to find the plan’s annual premium before adding other expenses.
The deductible is the amount you usually pay for covered services before the plan starts paying for many types of care. For example, with a $2,000 deductible, you may pay the first $2,000 of eligible medical costs yourself. However, plans often cover certain services before you meet the deductible.
A copay is a fixed charge for a covered service, such as $30 for a primary care visit or $15 for a generic prescription. Coinsurance is a percentage of the covered bill. If your plan has 20% coinsurance, you pay $20 on a $100 allowed charge after applicable cost-sharing rules.
Since these costs vary by plan, be sure to review the Summary of Benefits and Coverage for each plan before enrolling. Don’t assume every service follows the deductible. You can track your deductible through the insurer’s member portal or saved claim records.
Use the out-of-pocket maximum to measure financial risk.
The out-of-pocket maximum is the most you pay during one plan year for covered, in-network services through deductibles, copays, and coinsurance. After you reach that limit, the plan generally pays 100% of covered, in-network care for the rest of the year.
Premiums don’t count toward this maximum. Neither do out-of-network services, noncovered care, or charges above the plan’s allowed amount. For 2026 Marketplace plans, the federal limit is $10,600 for self-only coverage and $21,200 for family coverage, although an individual plan may set a lower limit. Check the plan’s details in the HealthCare.gov out-of-pocket maximum guidance.
Ask yourself whether you could afford the plan’s maximum during a serious illness year. That figure shows your financial risk more clearly than the premium alone.
Estimate your total yearly cost in three scenarios.
- All-in-One Medical Organizer: Keep your healthcare journey in one place with our medical visit logbook for tracking symp…
- Organized by 10 Easy-to-Navigate Tabs: Includes sections for Current Information, Medical History, Medications, Provider…
- Spiral Binding for Easy Writing: Lays flat for convenient note-taking during appointments, allowing you to write comfort…
Start with this simple comparison:
Annual premium + expected medical spending = estimated yearly cost
This total is an estimate, not a guarantee. Compare it with the plan’s out-of-pocket maximum to understand the range of possible costs. Build three estimates for someone who rarely visits a doctor, someone who needs regular medical care, and someone managing a major condition or planned procedure. Include prescription costs, specialist visits, therapy, lab work, and likely out-of-pocket costs.
HealthCare.gov’s yearly cost estimates can make this comparison easier than reviewing premiums alone. Enter your ZIP code, estimated income, and household size to view available plans and estimated prices. You still need a Marketplace account and application to receive final prices and enroll.
Check What Each Plan Covers Before You Focus on Price
Under the Affordable Care Act, Marketplace health insurance must cover 10 essential health benefits categories. These qualified health plans include hospital care, emergency services, maternity care, mental health treatment, prescription drugs, lab services, preventive care, and rehabilitative services. However, plans can still differ widely in cost sharing, service limits, networks, and approval requirements.
Metal levels mainly describe how you and the insurer divide covered medical costs. A Bronze plan usually shifts more costs to you when you receive care, while a Gold or Platinum plan generally charges higher premiums and less at the point of service. The metal level doesn’t guarantee identical benefits across each health plan, even when plans come from the same insurer.
Seek services you expect to use.
Review each plan’s rules for primary care, specialist visits, urgent care, emergency care, hospital stays, mental health care, maternity care, preventive care, lab work, imaging, physical therapy, and durable medical equipment. Preventive care may receive different treatment than diagnostic tests, even when both happen during a checkup.
Be aware of details that can change your actual price:
- A service may have a separate deductible before the plan contributes.
- Copays may apply only to a limited number of visits each year.
- Coinsurance may begin after you meet the deductible.
- Prior authorization may be required before imaging, therapy, hospital care, or equipment.
- Some preventive services may be covered before the deductible, while related diagnostic care is not.
Before enrollment, review your benefits and download the Summary of Benefits and Coverage for every plan. This summary of benefits includes standard coverage examples, which can help you see how a plan handles diabetes care and childbirth.
Check prescription formularies, drug tiers, and restrictions.
Coverage can vary between plans from the same insurer. Search each plan’s formulary using the exact medication name, dosage, and form you take. Then check whether the drug falls on a preferred or nonpreferred tier.
Your review should also identify prior authorization, step therapy, quantity limits, specialty-drug rules, mail-order requirements, and preferred pharmacies. A medication may be technically covered but still carry high coinsurance or require you to try another drug first. Medicare Advantage plans follow a different coverage and enrollment system, so don’t apply Marketplace formulary assumptions to them.
A low-premium plan can cost more overall if it places an important medication on a high tier or excludes it from the formulary.
Separate covered benefits from network limits
A plan can cover a service while limiting which doctors, hospitals, labs, or facilities you can use. Covered care means the benefit exists under the policy. Affordable in-network care means you can receive it from a contracted provider at the plan’s lower cost-sharing rate.
Use the insurer’s directory to find a doctor, then confirm that your specific physician, preferred hospital, pharmacies, and regular labs participate in the provider network. Before enrolling, find a doctor or facility by calling the provider directly, since directories can contain outdated information. Also check referral rules, prior approval, telehealth coverage, travel benefits, and out-of-area care. Track your deductible as cost sharing accumulates during the year. Marketplace plans must cover emergency services, including emergencies at out-of-network facilities, but routine follow-up care may follow stricter network rules.
Compare Health Plan Networks and Plan Types
A plan’s Bronze, Silver, Gold, or Platinum label describes how you and the insurer split covered costs. It doesn’t tell you whether your preferred doctor accepts the coverage. A provider network is a separate health insurance decision, and it can affect your convenience and total yearly cost.
Verify your doctor’s, hospital’s, and specialist’s plan by plan.
Search the insurer’s current provider directory using the exact plan name, not just the insurance company’s name. Use the directory to find a doctor, specialist, hospital, or other provider near you. One insurer may offer several Marketplace options with different networks in the same ZIP code.
Check your primary care doctor, specialists, preferred hospital, behavioral health providers, urgent care centers, and preferred labs. When you find a doctor, call the office and insurance company to confirm participation in that specific plan. Ask whether the provider is in network for the upcoming coverage year. A statement such as “we accept that insurer” may not identify the right network.
Provider directories can contain outdated information. Confirm participation before enrollment, then check again before important treatment, such as surgery, childbirth, cancer care, or a planned hospital admission. Keep the representative’s name, the date of the call, and any reference number with your plan records.
Understand HMO, PPO, EPO, and POS access rules.
HealthCare.gov identifies the plan type in Marketplace listings, and you can review its official comparison of plan types. The basic differences are
- HMO plans often use local networks. You may need to choose a primary care doctor and get a referral before seeing a specialist. Routine out-of-network care usually isn’t covered.
- PPO plans generally offer broader access without specialist referrals. They may pay part of an out-of-network claim, but you usually pay more.
- EPO plans generally cover routine care only from in-network doctors, specialists, and hospitals. Emergency care is the main exception.
- POS plans combine features of HMOs and PPOs. You may need referrals for specialists, while the plan may provide some out-of-network benefits at a higher cost.
These labels provide a useful starting point, but they don’t tell the whole story. Read the plan’s provider directory, Summary of Benefits and Coverage, and Evidence of Coverage. Review your benefits before you enroll.
Medicare Advantage plans are different from Marketplace HMO, PPO, EPO, and POS offerings. Don’t assume that network rules for one coverage type apply to another.
Match network size to your life and travel needs
A narrow network from a local health plan may work well if you receive most care near home. However, it can create extra costs or delays if you travel often, attend college in another state, work remotely, or receive treatment in several cities.
Before choosing, ask:
- Which hospitals and specialists are nearby?
- Can you locate a doctor when traveling or seeing a specialist in another city?
- How many urgent care locations are available?
- Does the plan offer telehealth or virtual care visits for the services you use?
- What happens when you need routine care away from home?
- How does the plan handle emergencies while traveling?
Marketplace plans must cover emergency services, including emergency care at an out-of-network hospital. Routine follow-up care may still require in-network providers, so emergency protection doesn’t replace a workable everyday network.
Post Title: How to Compare Coverage and Total Costs
Meta Description: Compare coverage by total costs, provider networks, plan types, prescriptions, deductibles, and out-of-pocket limits.
Choose the Metal Tier That Fits Your Health and Budget
ACA metal tiers in health insurance describe cost sharing, not the quality of care. Under the Affordable Care Act, Bronze, Silver, Gold, and Platinum plans must cover the same essential health benefits, but they divide covered medical expenses differently on average.
| Metal tier | Plan pays | Member pays |
|---|---|---|
| Bronze | 60% | 40% |
| Silver | 70% | 30% |
| Gold | 80% | 20% |
| Platinum | 90% | 10% |
These percentages are averages across covered services. Your actual costs depend on the plan, network, deductible, prescriptions, and type of care. Before choosing a tier, track your deductible and compare how quickly you may reach it.
When a Bronze plan may make sense
Bronze plans often have the lowest monthly premiums, but they usually charge more when you need treatment. Higher deductibles, coinsurance, and out-of-pocket limits can make a routine illness or hospital visit expensive.
This tier may fit you if you expect few appointments, take little or no medication, and have enough savings to handle a large deductible or unexpected medical bill. Still, don’t judge the plan by its premium alone. Review how it handles preventive care, primary care, urgent care, prescriptions, lab work, and specialist visits.
Check the full out-of-pocket maximum as well. Premiums don’t count toward that limit, and you must generally stay in the network to receive the plan’s strongest cost protection. HealthCare.gov’s metal-tier guide explains how these categories divide costs.
Why Silver plans deserve a closer look
Silver plans often balance monthly premiums with moderate cost sharing. They also deserve special attention because eligible shoppers can receive financial assistance, including cost-sharing reductions, only by choosing a Silver plan.
These savings can lower your deductible, copays, coinsurance, and out-of-pocket maximum. In some cases, a Silver plan with extra savings can provide much stronger cost protection than its standard 70% plan-paid average suggests.
Eligibility depends on your household size, income, tax information, and federal rules. Don’t guess based on last year’s income or a rough estimate. Complete the application to see whether you qualify and what your actual costs would be. HealthCare.gov’s cost-sharing reduction information provides the official enrollment guidance.
When gold or platinum can cost less overall
Gold and Platinum plans usually charge more each month, but they may reduce what you pay during medical care. That difference can matter if you expect frequent visits, ongoing therapy, expensive medications, specialist care, or a planned procedure.
When you compare health insurance plans, consider the annual premium together with your expected medical costs. A higher premium can be the better financial choice when it replaces large deductibles or high coinsurance. Review both your likely yearly cost and the plan’s worst-case in-network exposure before choosing.
Apply Financial Help and Make the Final Plan Choice
Once you understand the benefits, networks, and cost sharing that health insurance offers, apply for financial assistance before making your final choice. The best option fits your care needs while keeping routine bills and emergency costs manageable.
Compare the net premium after tax credits
Compare what you’ll actually pay each month, not just the listed premium. Premium tax credits from the marketplace can reduce monthly payments for eligible enrollees. The quoted amount depends on your ZIP code, age, household size, and estimated income for individual and family plans.
These credits apply to qualified health plans purchased through the official health insurance marketplace. An off-exchange shopping tool may show similar coverage, but it generally won’t include Marketplace assistance. Check whether your application goes through HealthCare.gov’s official Marketplace or your state’s exchange before comparing prices.
Multiply the net monthly premium by 12, then add your expected medical spending. CMS projections for 2026 offer useful guidance, but they aren’t a personal quote. Your completed Marketplace application determines your eligibility, subsidy, and final price.
Report income, household, marriage, address, or coverage changes during the year. The Marketplace compares your advance tax credit with your actual annual income when you file taxes. An outdated estimate could leave you owing money or receiving less help than you qualify for. HealthCare.gov’s reporting guidance explains why updates matter.
Use a side-by-side plan comparison checklist.

- Keep important documents safe: A document organizer designed to protect papers from getting lost. Store birth certificat…
- Easy to organize and find: Folders with pockets and a table of contents help track where documents live, while 33 hand-i…
- Fits documents of various sizes: This document binder includes 3 vertical and 3 horizontal envelopes for 8.5 x 11 inch p…
Record the same information for every plan. A spreadsheet or simple note can keep one attractive premium from hiding a costly gap.
- Write down the net monthly premium and annual premium.
- Record the deductible, coinsurance, and out-of-pocket maximum.
- Compare primary care and specialist copays.
- Compare prescription drugs, pharmacy rules, and medication restrictions.
- Check whether your provider network includes your doctors, hospitals, specialists, labs, and pharmacies.
- Use the provider directory to find a doctor before enrolling.
- Review your benefits, including referral rules and prior authorization requirements.
- Check whether the plan pays anything for routine out-of-network care.
- Estimate your yearly out-of-pocket costs under low-use, regular-care, and major-care scenarios.
- Save the summary of benefits, provider directory, formulary, and plan documents.
- Track your deductible through the insurer’s member portal, where you can also review claims and plan documents.
After comparing the figures, ask whether the plan still works during a serious illness or hospital stay. Keep copies of your notes because plan details and provider directories can change.
Know when and where to enroll.
Browsing plans, submitting an application, selecting a plan, and receiving an effective date are separate steps. You may browse without enrolling, but you must complete the application, choose a plan, and pay any required first premium before coverage begins.
Check the current Marketplace enrollment dates and deadlines during open enrollment. Federal Marketplace shoppers use HealthCare.gov. If your state runs its exchange, use that state’s official marketplace to compare a local health plan. Deadlines and coverage start dates may differ.
Open enrollment isn’t the only option. A qualifying life event, such as losing job-based coverage, marriage, birth, or adoption, may create a special enrollment period. A deadline can determine whether coverage starts January 1 or later, so don’t wait until the final day to apply.
Choose the health plan that protects your health needs and emergency savings. After enrollment, save your member ID cards and confirmation documents.
Frequently Asked Questions
Is the plan with the lowest premium always the cheapest option?
No. A lower premium may come with a higher deductible, copays, coinsurance, or out-of-pocket maximum. Compare the premium plus your expected medical spending for the full year.
What is the most important cost to compare after the premium?
Review the deductible and out-of-pocket maximum together. The deductible affects what you may pay before the plan contributes to many services, while the out-of-pocket maximum shows your potential in-network cost exposure during a serious illness.
How can I confirm that my doctor is covered?
Search the insurer’s provider directory using the exact plan name, then call both the doctor’s office and the insurer to confirm participation. Ask whether the provider is in-network for the upcoming coverage year, as directories can contain outdated information.
Should I choose a Bronze, Silver, Gold, or Platinum plan?
The right metal tier depends on your expected medical needs, budget, and eligibility for financial assistance. Bronze plans generally have lower premiums and higher cost sharing, while Gold and Platinum plans usually have higher premiums and lower costs when you receive care; eligible shoppers may receive cost-sharing reductions only with a Silver plan.
Do Marketplace plans cover prescriptions and emergency care?
Marketplace plans must cover prescription drugs and emergency services, but formularies, drug tiers, restrictions, and cost sharing vary by plan. Emergency care is generally covered even at an out-of-network facility, while routine follow-up care may require in-network providers.
Conclusion
When you compare health insurance plans, look beyond the monthly premium. Compare at least two or three plans using official Marketplace information, then weigh estimated yearly costs, deductibles, copays, coinsurance, care access, medication coverage, financial assistance, and the out-of-pocket maximum. The best health insurance is coverage that remains affordable when care is needed.
Before choosing a plan, find a doctor and confirm that your hospitals and medications are covered. Review your benefits for deductibles, copays, coinsurance, and the out-of-pocket maximum. If you’re comparing Medicare Advantage plans, use Medicare-specific information rather than assuming Marketplace rules apply. The best plan isn’t always the cheapest plan. It’s the one you can use for your medical needs and afford when a serious medical bill arrives.