
In This Article
Buying a home can make every credit alert feel louder than it should. Still, simple ways to improve credit score quickly exist when you focus on the items that can change your reported profile soon, rather than chasing expensive credit hacks.
No legitimate tactic guarantees an overnight score jump or a mortgage approval. Lenders can use different scoring models and requirements. However, checking your reports, lowering card balances, protecting payments, correcting errors, and avoiding new debt can put you on firmer ground before you apply.
Simple Ways to Improve Credit Score Quickly Before You Apply for a Mortgage
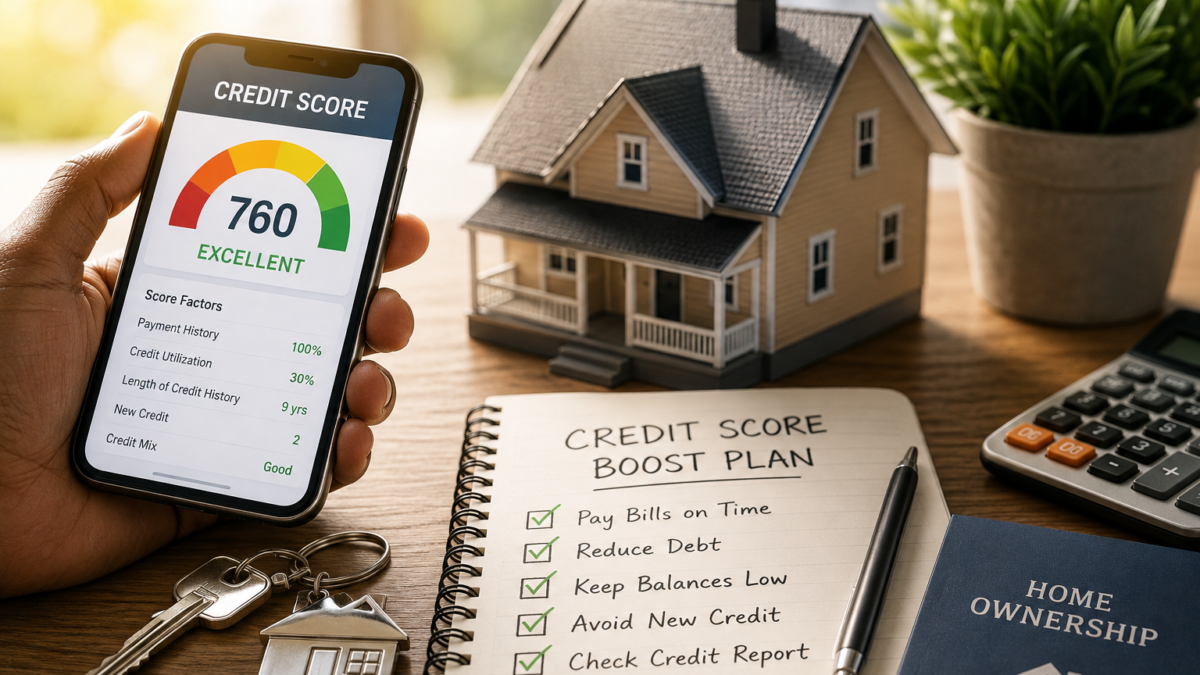
FICO commonly weighs payment history at 35%, amounts owed at 30%, length of credit history at 15%, new credit at 10%, and credit mix at 10%. That makes your payment record and revolving card balances the first places to look when your home-buying timeline is close.
Start with the money already moving through your accounts. A balance payoff may appear on a future credit report after your card issuer updates it. Meanwhile, an on-time payment keeps a fresh late mark from becoming another obstacle.
Lower Your Credit Utilization Before Your Statement Closes
Credit utilization is your reported balance divided by your credit limit. You need to watch it on each card and across all cards.
For example, a $900 balance on a card with a $1,000 limit equals 90% utilization. Paying it down to $200 drops that card to 20%. Pay before the statement closing date when possible, because that is often when issuers report a balance.
Put extra cash toward cards with the highest utilization first. Then avoid purchases that send those balances back up. These simple ways to improve credit score quickly are usually more useful before a mortgage than opening a new card for more available credit.
Protect Your Payment History From New Damage
Bring past-due accounts current if you can. Next, set autopay for at least the minimum due on every open account, then confirm your bank balance can cover it.
Call a creditor before a payment is late if cash is tight. One new late payment can cause more harm than a modest gain from paying down a card. Also, don’t close an older card without a clear reason. Its age and unused credit limit may help your profile.
Accurate negative information cannot be legally removed because a credit repair company asks for it to disappear.
Improve Credit Score Quickly by Fixing Credit Report Errors
Pull all three reports early, while you still have time for a correction to work through the system. AnnualCreditReport.com is the authorized site for free reports from the nationwide bureaus, and you can request each report weekly.
Mortgage underwriting can reveal a problem at the worst moment, when you have already found a house and set a closing target. A clean review now gives you time to document and dispute real mistakes.
Review Equifax, Experian, and TransUnion Separately
Equifax, Experian, and TransUnion don’t always show the same information. Checking only one report can leave an incorrect account or late payment hidden on another.
Look for accounts you don’t recognize, wrong balances, duplicate debts, false late payments, outdated personal details, and accounts still listed as open after closure. Save each report as a PDF or print it. Then make a short written list of every item that needs attention.
The site’s explanation of credit reports can help you identify the account, inquiry, and public-record sections before you begin.
Dispute Inaccurate Information With the Bureau and Furnisher
Disputes are free. Tell each bureau exactly which item is wrong, explain the correction you want, and include copies of supporting documents. Keep originals and records of what you submitted.
Also contact the company that supplied the information when it fits the error. Credit reporting companies generally investigate within 30 days, although some cases can take longer. Afterward, check the updated report instead of assuming the change appeared everywhere.
The official dispute guidance explains how to start the process. Don’t pay a company that promises to erase information that is accurate.
How to Improve Credit Score Quickly Before a Mortgage
There is no universal minimum credit score for every mortgage. Loan programs and individual lenders set their own standards, and a lender may review more than one score or report.
Ask your loan officer which scoring model, documents, and timeline will apply. That conversation turns vague score anxiety into a practical plan. It also helps you avoid changes that could delay underwriting.
Ask Your Loan Officer About Timing and Rapid Rescoring
A lender may discuss rapid rescoring after you document a paid-down balance or a corrected reporting error that has not reached your credit report yet. This lender-ordered service can speed up an update, but you usually can’t order it yourself.
Rapid rescoring does not create new credit information. It also can’t promise a higher score or loan approval. Coordinate with your lender rather than paying an outside company for an unsupported guarantee.
Pause New Credit Applications and Big Purchases
Until your mortgage closes, avoid opening cards, financing a car, closing accounts, co-signing a loan, or making major purchases unless your lender approves the move. Hard inquiries, new balances, and fresh monthly payments can affect both your score and debt-to-income ratio.
Keep several months of statements organized. Pay every bill on time, and maintain a small emergency cushion. A steady plan beats a frantic last-minute reshuffle.
Keep Your Home-Buying Credit Plan Steady
Start with all three reports, dispute real errors, reduce revolving balances, and automate every payment. Those simple ways to improve credit score quickly can affect what appears in the next reporting cycle, while consistent habits build the stronger profile you want to keep.
Visit AnnualCreditReport.com, make a realistic payoff plan, and speak with a mortgage professional before submitting applications. Your score doesn’t need magic. It needs clean information, lower balances, and no new surprises.
