In This Article
Retirement saving isn’t an all-or-nothing decision. How to save for retirement begins with the next practical step, even if that step is $25 from your next paycheck.
You may be in your 20s with student loans, your 40s with a mortgage, or close to retirement with little set aside. Different incomes and responsibilities call for different choices, but a simple plan still works: pick a target, use the right account, automate contributions, and revise the plan as life changes.
Key Takeaways
- Start with a monthly amount you can repeat, then increase it as income grows.
- Capture every available employer match before adding money elsewhere.
- Use tax-advantaged accounts that fit your job, income, and tax situation.
- Keep emergency cash separate from long-term investments.
- Review contributions, fees, and beneficiaries once or twice each year.
Start With a Clear Retirement Savings Target
A retirement number can feel enormous because it bundles decades of living costs into one figure. Begin closer to home. List your current retirement balance, household income, monthly spending, high-interest debt, employer benefits, and the age when you hope to stop full-time work.
A rough goal beats waiting for a perfect calculation. Many planners use 10% to 15% of gross income as a long-term savings benchmark, including an employer match. However, a smaller consistent contribution still builds momentum. Starting at 3% gives you a base to raise after a promotion, a paid-off loan, or a lower childcare bill.
Want more help building your retirement plan? The Retirement Planning QuickStart Guide provides a structured introduction to retirement planning, investments, and portfolio management.

Suppose you want to add $120,000 to retirement savings over 20 years, before investment growth. Divide that amount by 240 months. The starting target is $500 per month. If that doesn’t fit today, save $100 and schedule a future increase. Progress begins when the plan meets your actual budget.
Build a small emergency fund alongside retirement contributions. Otherwise, a car repair or medical bill may force you to use a credit card or raid an account meant for later. Paying off high-interest debt also frees cash that can stay invested for years.
For current annual caps, consult the IRS retirement contribution limit update before setting an aggressive savings goal.
How to Save for Retirement at Any Age
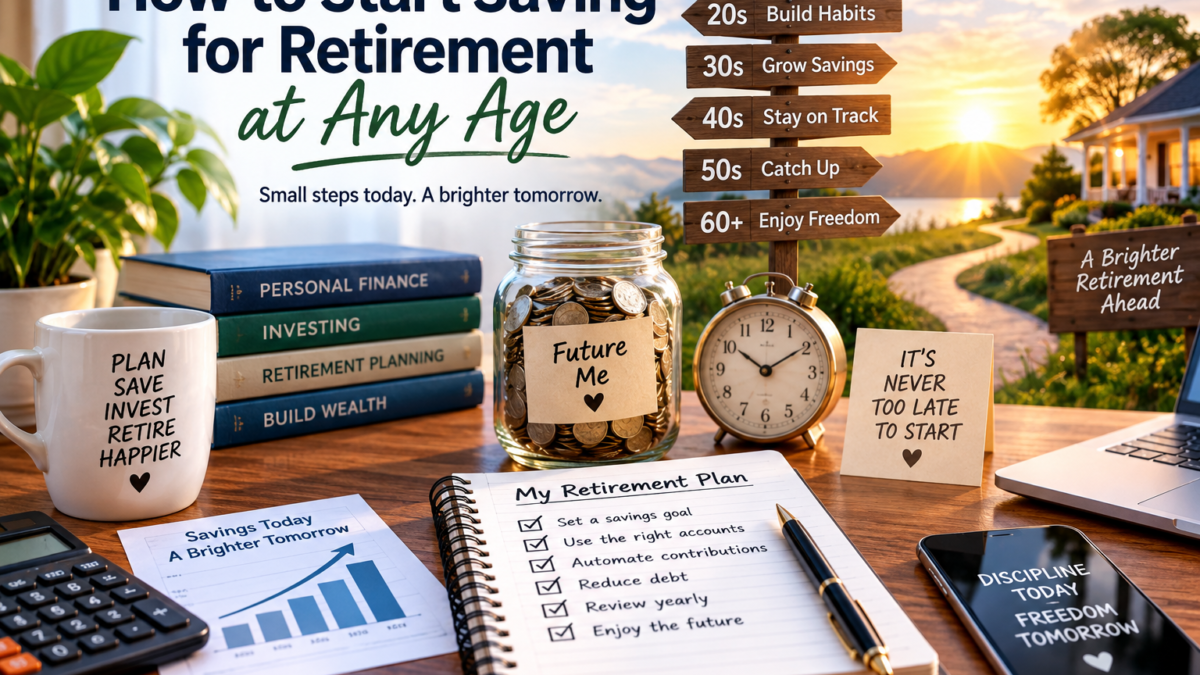
Your best move depends on your time until retirement, income, and workplace benefits. Age helps shape the plan, but it doesn’t lock you into a formula.
In Your 20s and 30s, Build the Habit and Use Time
Time gives investment returns more years to compound. First, contribute enough to a 401(k) to receive the full employer match. Then consider a Roth IRA if you qualify, especially if your current tax rate is lower than you expect in retirement.
A 3% to 5% contribution rate is a stronger start than waiting for 15% to feel comfortable. Increase the percentage after every raise, then choose a diversified mix that fits a long time horizon. A low-cost target-date fund can offer a simple default.
In Your 40s, Increase Contributions With a Focused Plan
Mortgage payments, children, and college costs can crowd the budget in your 40s. Still, check the gap between your projected savings and likely retirement spending. A gap is a planning signal, not a verdict.
Raise contributions by one percentage point at a time. Also review investment fees and asset allocation, because both affect the money that stays in your account. When cash flow permits, pair a workplace plan with an IRA instead of relying on one account alone.
In Your 50s and 60s, Use Catch-Up Contributions and Reduce Risk Carefully
Workers age 50 and older can often make catch-up contributions to 401(k), 403(b), and IRA accounts. The rules and limits change, so check the IRS guidance on catch-up contributions and confirm what your plan allows.
Working longer, delaying Social Security when it suits your situation, and trimming future expenses can improve the picture. Reduce investment risk gradually, based on when you’ll need the money. A single bad market month isn’t a reason to sell long-term investments in fear.
A late start calls for clearer priorities and higher savings when possible, not a rushed attempt to make up years of growth with risky bets.
Choose Retirement Accounts and Automate Contributions
The account matters because taxes, withdrawal rules, and employer benefits affect what your savings can do. Start with the plan attached to your paycheck if it includes a match. That match is part of your compensation, and leaving it unused means leaving pay on the table.
Compare the Accounts Before You Fund Them
A 401(k) or 403(b) lets employees contribute through payroll. Traditional contributions may reduce taxable income today, while qualified Roth withdrawals are generally tax-free because you contribute after tax. Traditional and Roth IRAs offer similar tax treatments outside an employer plan, though Roth IRA eligibility depends on income.
For readers who want a deeper understanding of retirement accounts and long-term investing, The Bogleheads’ Guide to Retirement Planning covers saving strategies, investment choices, and retirement planning principles.

Self-employed workers may consider a SEP IRA or solo 401(k). For 2026, the IRS lists a $7,500 combined annual limit for traditional and Roth IRAs, with a higher limit for eligible catch-up contributors. Review the IRA contribution limits before depositing money.
Put Contributions on Autopilot
Set the contribution to leave your paycheck shortly after payday. If you use an IRA, schedule an automatic transfer after your regular income lands. A 1% annual increase can feel modest in a monthly budget while changing your long-term savings rate.
Check fund fees, available investments, income limits, and withdrawal rules before opening or changing an account. If choosing funds feels overwhelming, a target-date fund or automatic rebalancing feature can keep the mix aligned with a planned retirement year. The IRS also publishes 401(k) contribution limits for workers comparing payroll deductions with annual caps.
Make Your Retirement Plan Work Through Setbacks and Market Changes
A retirement plan has to survive ordinary disruptions. Irregular income, caregiving, a job change, and a sudden repair bill can all interrupt contributions. Pausing for a hard month is manageable. Forgetting to restart is what lets a short setback become a long delay.
Separate Emergency Cash From Investment Money
Keep near-term emergency savings in a safe, accessible account. Retirement investments have a different job: they need time to grow through market ups and downs. When markets fall, selling diversified long-term holdings can turn a temporary decline into a permanent loss.
During a job change, review the old workplace account carefully. You may be able to leave it in place, roll it into a new employer plan, or move it to an IRA. Compare fees, investment choices, and rollover rules before acting.
Review the Plan on a Simple Schedule
Once or twice a year, open every account and check the basics:
- Confirm your contribution rate and whether you receive the full employer match.
- Review investment fees and whether your asset mix still fits your timeline.
- Update beneficiaries after marriage, divorce, births, or deaths.
- Compare your savings balance with your target, then make one practical adjustment.
For people close to retirement, annual contribution limits can include higher amounts at certain ages. Check the IRS cost-of-living limit table rather than relying on an old article or memory.
Frequently Asked Questions
Should I save for retirement if I have credit card debt?
Paying down high-interest credit card debt usually deserves priority because the interest can outpace likely investment returns. Still, contribute enough to capture an employer match if you can. That match may provide an immediate return that is hard to replace.
Can I start with only $25 per paycheck?
Yes. A small automatic contribution creates the habit and gives you a place to direct future increases. Raise it after a pay increase or when another expense disappears, even if the next step is only $10 more.
What happens to my 401(k) when I leave a job?
Your money remains yours. You can often leave it in the former employer’s plan, roll it into a new plan, transfer it to an IRA, or cash it out. Cashing out can trigger taxes and penalties, so review the consequences before choosing that route.
Do I need a financial advisor to begin?
No. You can begin with your employer’s plan materials, automatic contributions, and a diversified fund. An advice-only fiduciary financial planner or qualified tax professional can help when you face complex taxes, pensions, stock compensation, or major withdrawal decisions.
How much of my portfolio should be in stocks near retirement?
There isn’t one percentage that fits every household. Your allocation should account for other income, expected spending, pensions, Social Security, and how soon you need withdrawals. A target-date fund can offer a starting point, but read its holdings and glide path.
Build the Next Contribution Into Your Life
Retirement saving is a process, not a one-time test. Calculate a starting amount, capture any employer match, and automate the next contribution so the plan doesn’t rely on monthly willpower.
If you started late, focus on choices you can control. Increase savings when your budget allows, use catch-up contributions if eligible, review future expenses, and get qualified financial or tax guidance when the decisions become complex.
A modest contribution made consistently can become a dependable part of your future income.