In This Article
Your financial life is a snapshot, not a scorecard. Learning how to calculate net worth gives you a clear picture of what you own, what you owe, and the difference between those two numbers.
Learning how to calculate net worth takes a few records and basic math. You will list your assets, total your debts, subtract one from the other, then revisit the figure over time to see where your money is moving.
Key Takeaways
- Net worth equals the current value of your assets minus all outstanding liabilities.
- Use a consistent date and current balances, not what you originally paid.
- Include major assets, such as savings, investments, property, and vehicles.
- Count every debt, including mortgages, credit cards, student loans, and taxes owed.
- Track the number over time to guide decisions, not to judge yourself.
Calculate net worth
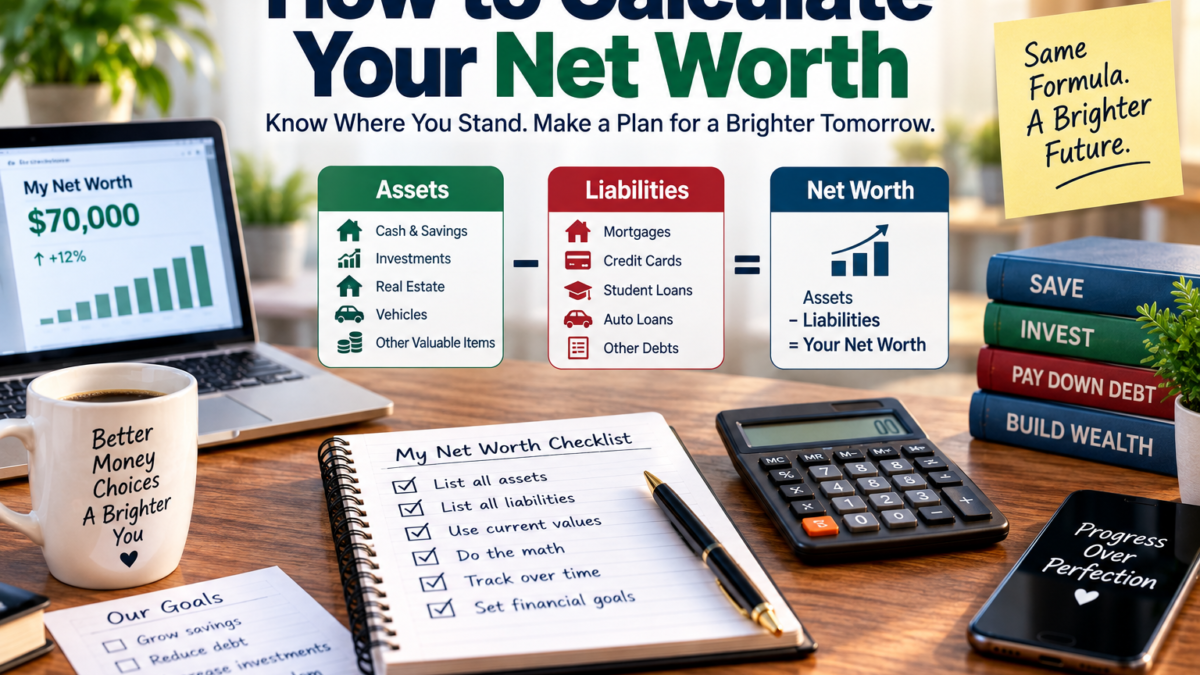
The formula is straightforward: net worth = total assets minus total liabilities. An asset has monetary value, while a liability is money you owe. Bankrate’s net worth calculator uses the same simple relationship between what you own and what you owe.
Choose one date, such as the last day of the month. Then gather bank statements, loan balances, investment account totals, and any records that show an item’s current value.
- List every asset you own and assign each one a current, realistic value.
- Add those values to find your total assets.
- List all debts and record the amount currently outstanding.
- Subtract total liabilities from total assets.
For example, $250,000 in assets minus $180,000 in liabilities leaves a net worth of $70,000. A spreadsheet works well because it preserves past calculations, but a calculator or paper worksheet can do the job.
A financial calculator is useful for reviewing debts, savings, investment growth, loan payments, and other calculations alongside your net worth.

- HP 12C PLATINUM: FOR FINANCE PROFESSIONALS – Designed for advanced users in banking, investing, and corporate finance. T…
- 130+ FUNCTIONS FOR ADVANCED ANALYSIS – Calculate loan payments, interest rates, bond prices, amortization, depreciation,…
- RPN OR ALGEBRAIC ENTRY + UNDO KEY – Choose between Reverse Polish Notation or standard algebraic logic. Includes both Un…

- PRO SIZE & PREMIUM EDITION – Clever Fox Planner PRO Premium combines a spacious A4 format; advanced planning tools; unda…
- UNDATED & UNIQUE LAYOUTS – An important feature of this planner is that it is undated; so, unlike most dated planners, y…
- WEEKLY, MONTHLY & FINANCIAL PLANNING – This life planner combines spacious weekly planning pages, monthly calendars, goa…
List Every Asset at Its Current Value
Start with cash in checking and savings accounts. Next, add retirement plans, brokerage accounts, certificates of deposit, real estate, vehicles, business ownership, cryptocurrency, and valuable personal property.
Use today’s value, not the purchase price. Your investment account statement shows its current balance. For a home or car, use a conservative market estimate based on recent comparable sales or trade-in values. Investopedia’s explanation of net worth offers a useful reminder that assets are items you own with monetary value.
Furniture, clothing, kitchenware, and everyday electronics usually have little resale value. Leave them out unless they are antiques, collectibles, or other items with a meaningful resale market.
Add Up Mortgages, Loans, and Other Liabilities
Liabilities include credit card balances, mortgages, auto loans, student loans, medical bills, personal loans, tax debt, and money owed to family or friends. Record the current payoff or account balance, rather than the loan’s original amount.
A mortgage belongs on this list even though your home is also an asset. For instance, a $400,000 home with a $280,000 mortgage adds $400,000 to assets and $280,000 to liabilities. The difference, $120,000, is your home equity.
Estimates are fine when exact values are unavailable. However, use the same method every time so changes in your net worth reflect real progress instead of shifting guesses.
Calculate Net Worth: What Does the Number Mean?
A positive result means your assets exceed your debts. A result of zero means they match. A negative figure means your debts currently exceed your assets.
None of those outcomes says anything about your character or work ethic. A new graduate with student loans or a buyer with a new mortgage can have a negative net worth while building a stable future.
Net worth differs from income. Income measures money coming in through wages, self-employment, investments, or benefits. Net worth shows the value you have built after debts. MoneySmart’s net worth calculator frames the calculation as a way to assess your financial position.
Positive, Zero, and Negative Results
A positive net worth can give you choices, but it may include assets that take time to sell. Your primary home, retirement accounts, and collectibles may hold substantial value without covering a sudden expense.
That is where liquid net worth helps. It focuses on cash and assets you can turn into cash fairly quickly, often leaving out a home, vehicles, and hard-to-sell property. Age, location, household size, and life stage also shape the number, so tracking your own direction matters more than comparing it with an average.
See How Home Equity, Retirement Savings, and Debt Change the Result
Say your home’s market value stays at $400,000 for a year. If you reduce the mortgage from $280,000 to $270,000, your net worth rises by $10,000 because your equity increased.
Retirement contributions also add to assets, while high-interest credit card debt can pull the total down quickly. Still, stock prices and home values move. One calculation is a photograph of a moment, not a permanent verdict.
A change in net worth matters most when it comes from habits you can repeat, such as steady saving and lower debt.
Calculate Net Worth Regularly and Track Your Progress
Most people benefit from a quarterly or twice-yearly update. Monthly reviews can work if you are paying down debt, saving for a home, or managing irregular income. Record the calculation date, use the same categories, and apply the same valuation rules each time.
Keep your file private. Use password-protected financial tools, avoid entering the same account twice, and check that joint accounts are labeled as joint. A net worth formula guide with examples can help when you want to recheck your categories.
Look for Trends Instead of Chasing One Number
A useful review shows movement. Your cash reserve may be growing, credit card debt may be shrinking, or retirement contributions may be accumulating. Those changes tell a clearer story than one large total.
Compare numbers from the same point in each month or year. Otherwise, a credit card balance posted before payday or a market dip on one random day can distort the picture.
Avoid These Common Mistakes When You Calculate Net Worth
Original purchase prices often make assets look stronger than they are. A five-year-old car and a home bought years ago need current values. On the other hand, skipping a small medical bill, tax balance, or old credit account makes liabilities look too low.
Don’t count an asset twice, such as adding the value of a brokerage account and its individual funds separately. Also, keep individual and household calculations distinct unless you clearly label the worksheet.
Avoid inflated values for personal belongings. Short-term market changes also don’t call for panic. The point is a reliable record, not a perfectly polished number every week.
Frequently Asked Questions
Should I Include My Car When I Calculate Net Worth?
Yes, you can include a vehicle as an asset using a realistic private-party or trade-in value. Put any remaining auto loan under liabilities.
Some people leave out depreciating personal items for a simpler and more conservative calculation. Either choice works if you use it consistently.
Is a Negative Net Worth Normal?
Negative net worth is common when student loans, credit card debt, or a new mortgage are larger than current assets. It is a starting point, not a failure.
Focus first on high-interest debt, a basic cash reserve, and regular payments. Small improvements compound when you repeat them month after month.
How Often Should I Check My Net Worth?
For most households, quarterly or twice-yearly reviews provide enough information without creating stress. Check sooner after a major event, such as a new job, home purchase, divorce, inheritance, or large debt payoff.
Daily investment checks can turn normal market movement into needless anxiety. Use a schedule that supports better decisions.
What Is the Difference Between Net Worth and Liquid Net Worth?
Total net worth includes everything you own with value, minus everything you owe. Liquid net worth focuses on assets you can access quickly, such as cash and many taxable investments.
A primary home, vehicles, retirement accounts, and difficult-to-sell property often stay out of liquid net worth. That narrower figure is useful when planning for emergencies.
Conclusion
The math behind how to calculate net worth stays simple: add current assets, add outstanding debts, and subtract. The first result may feel uncomfortable, but it gives you a clear place to begin.
Progress can come through smaller moves, including paying down costly debt, saving consistently, and making better choices about major assets. Your net worth is most useful when it gives you awareness and direction, not pressure to be perfect.